Parcion Parcion

The Millionaire's
Tax.

Washington State signed a 9.9% tax on high earners into law this spring. Whether it survives a court challenge and a November ballot vote is still an open question. Here's how families and business owners are getting ahead of it either way.

With Patrick Carter Director of Advanced Planning, Parcion Private Wealth
Listen to the full conversation
Download the audio
Patrick Carter
Patrick Carter
Director of Advanced Planning

Patrick Carter leads advanced planning at Parcion, working across estate planning, tax strategy, philanthropy, and long-term family governance. He started his career as a family therapist before law school, then spent a decade in estate and tax planning in Washington State.

Context on our conversation

Why we're talking about this now.

Washington State signed a new income tax on residents earning more than $1 million a year into law this spring. It doesn't collect a dollar until 2029, and a court case and a November ballot measure could still take it off the books entirely. That's exactly why Patrick Carter, Parcion's Director of Advanced Planning, says now is the time to start paying attention, not later, once the outcome is settled.

Carter walks through what the law actually does, why a graduated income tax has a real constitutional problem in Washington State, and what a multi-year runway before implementation actually buys a family that wants to plan instead of react.

He also gets specific about the one strategy most people ask about first: leaving the state. What changing your domicile really requires, what you're allowed to keep, and why doing it without the right advisors can cost far more than the tax itself.

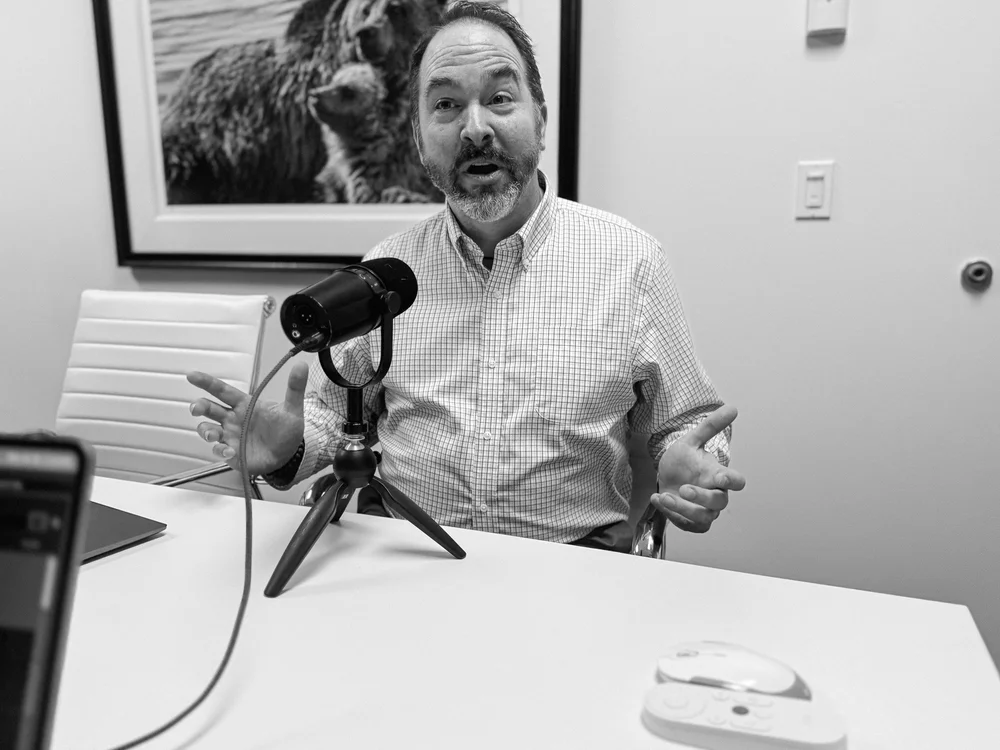
Patrick Carter recording the episode

What the Law Does.

$1M
Household income threshold
that triggers the tax
9.9%
Enacted rate on income
above the threshold
2028
Effective date, if it survives
the court and the ballot

Key takeaways

What to remember.

01

The law taxes Washington State residents at 9.9% on household income over $1 million a year, combining ordinary wages, restricted stock units, and capital gains into one aggregate figure.

02

This is law. Governor Ferguson signed SB 6346 on March 30, 2026, making it Washington State's first income tax since 1932. Whether it survives long enough to actually collect anything is a separate question.

03

Washington State's constitution has treated income as property since the 1930s, and property must be taxed the same way across the board. A graduated tax has historically failed that test, and a coalition led by former Attorney General Rob McKenna sued within two weeks of the signing to make exactly that argument.

04

The law doesn't take effect until January 1, 2028, with the first payments due in 2029. That's a multi-year runway, and families who use it to plan tend to land in a better position than families who wait for a final answer that may never fully arrive.

05

Changing domicile is the primary way to avoid the tax, but it's judged on facts and circumstances: banking, medical care, mailing address, driver's license, voter registration, and time actually spent in the state.

06

Two separate fights could still undo it: a constitutional lawsuit in Klickitat County Superior Court, and Initiative 645, a November 2026 ballot measure that would repeal the tax outright. Neither is resolved.
How it compares

Not the highest rate in the country. Possibly the highest in one city.

On its own, a 9.9% top rate doesn't put Washington State at the top nationwide. A few states already tax high earners more, one has already passed something nearly identical, and a longer list charge nothing at all.

Washington State
9.9%,
now law
Oregon
9.9%,
matches WA’s rate
California
13.3% top bracket
Nevada
$0 income tax
Arizona
2.5% flat
Wyoming
$0 income tax
South Dakota
$0 income tax
Texas
$0 income tax
Tennessee
$0 income tax
Florida
$0 income tax
New York
9.65–10.9%
New Jersey
10.75%,
over $1M
Massachusetts
9%,
already law
Taxes high earners at or above Washington State's enacted rate
Low or no state income tax

Worth noting

Massachusetts passed something close first: a 4% surtax on top of a 5% flat rate for income over roughly $1.1 million, nearly identical to what Washington State just enacted. Oregon and New Jersey tax income above $1 million at rates that match or exceed it too.

Cities worth watching

New York City residents stack a local income tax on top of the state's, pushing combined top rates toward 14.8%. Seattle's payroll tax structure adds its own pressure on employers with high-earning teams, though the size of that effect is more informally cited than formally verified.

The other side of the map

Nine states charge no income tax at all, and six of them are highlighted here. Arizona isn't one of them. Its flat 2.5% rate is real tax. But it's the state Parcion hears about most when this conversation turns to relocation.

Rates shown are top marginal figures as of 2026 and do not account for local taxes, deductions, or individual circumstances. Washington State's rate reflects SB 6346 as signed; it does not take effect until 2028 and remains subject to a pending court challenge and a November 2026 ballot measure. This is illustrative, not tax advice.

Preparing, Not Reacting — Parcion Private Wealth whitepaper cover

Free whitepaper

Preparing, Not Reacting.

Making sense of Washington State's new income tax: a planning perspective for business owners and wealth creators.

Residency and domicile planning, estate and gift strategy, common misconceptions and risks, and the framework we use to help families prepare instead of react, all in one download.

Download the whitepaper

"Ever since the 1930s, our state supreme court has held that income is property. The Washington State Constitution has very specific requirements for how property may be taxed, specifically that a class of property must be taxed the same way across all individuals."

Patrick Carter  ·  Director of Advanced Planning, Parcion Private Wealth

That single distinction, whether income counts as property under the state constitution, is the crux of the legal challenge now working through the courts. A separate fight is playing out at the ballot box too: Washington State voters decide the law's fate directly this November.

Our approach

Planning, not panic.

The law is on the books, but whether it survives contact with the courts, or with voters this November, is still genuinely unresolved. What we can do is help a family understand the landscape now, so decisions come from a plan instead of a headline.

For families who decide that changing domicile is the right answer, that decision touches banking, healthcare, estate planning, and business structure all at once. It has to be managed like a project, with every advisor working from the same plan.

Domicile is a project, not an impulse. Treat it like one.

Start the conversation early

January 1, 2028 sounds distant, but the planning window narrows quickly, especially if the court case or the November ballot measure resolves sooner than expected in either direction. Families who start now are choosing their timeline instead of scrambling on someone else's.

Understand what domicile actually requires

Banking relationships, medical providers, driver's license, voter registration, and time actually spent in the state all factor into the facts-and-circumstances test. There's no shortcut form.

Know what you keep

Leaving Washington State doesn't mean giving it up entirely. Families can keep property, visit grandkids, and spend meaningful time in-state, generally under half the year, without undoing the change.

Coordinate every advisor

Financial planner, estate attorney, and CPA all need to work from the same plan. Getting a domicile change wrong, and having the state pull you back in, means owing the original tax plus penalties and interest.

FAQ

Questions we're getting.

It's SB 6346, a 9.9% state income tax on Washington State household income above $1 million a year, signed into law by Governor Bob Ferguson on March 30, 2026. The definition of income is broad: ordinary W-2 wages, restricted stock units, and capital gains are all aggregated toward the threshold. It's set to take effect January 1, 2028, with the first returns due in 2029.
That's genuinely contested, and it's already in court. Since the 1930s, the Washington State Supreme Court has held that income is property, and the state constitution requires that a class of property be taxed the same way for everyone, at no more than 1%. A group led by former Attorney General Rob McKenna sued in April 2026 arguing the law's graduated structure violates that rule. The case is expected to reach the state Supreme Court by early 2027.
Domicile is decided by a facts-and-circumstances test, not a single form. The state looks at where you actually live: your banking relationships, your medical providers, your mailing address, your driver's license, your voter registration, and how much of the year you spend in Washington State versus elsewhere. Generally, spending less than half the year in Washington State strengthens the case that you've genuinely relocated.
Yes. Initiative 645 qualified for the November 2026 ballot and would repeal the law. Governor Ferguson is leading the campaign against it, and both sides are treating it as one of the most closely watched, expensive ballot fights in the state this year. Until that vote happens, and until the separate court case resolves, the law's future is genuinely unsettled.
January 1, 2028, with first returns and payments due in 2029, assuming it survives both the pending court case and the November ballot measure. Either one could change that timeline before the state collects a dollar.

Further reading

More from Parcion.

Planning Guide  ·  Parcion Private Wealth

Opportunity Zones 2.0

Another tool in the post-sale and post-liquidity planning conversation, now a permanent part of the tax code and worth understanding alongside strategies like domicile change.

Read the guide

Talk with us

Plan for it before the outcome is certain.

If you're a Washington State resident with income near this threshold, the best time to understand your options is now, while there's still runway before 2028. We're happy to walk through what this law, win or lose in court and at the ballot box, could mean for your specific situation.

Schedule a conversation

This page is for informational purposes only and does not constitute tax, legal, or investment advice. The legislation discussed, SB 6346, has been signed into law but remains subject to a pending constitutional challenge and a November 2026 ballot measure that could repeal it; its effective date and ultimate fate could still change. Parcion Private Wealth is an SEC-registered investment adviser. Please consult qualified tax and legal counsel before making any decisions based on this content.

© 2026 Parcion Private Wealth. All rights reserved.  ·  parcionpw.com  ·  This material is for informational purposes only. Not investment, tax, or legal advice.
Parcion
0
Skip to Content
Parcion Private Wealth